Introduction
If the place of supply of a service purchased from a supplier outside the UK is deemed to take place in the UK, UK output VAT is due to HMRC under the reverse charge mechanism.
The supplier should not charge VAT on their invoice. You (the purchaser) need to account for UK output VAT (and also input VAT) when you enter the invoice.
Enter the purchase
The invoice should be entered as a journal (JRN) transaction that accounts for the expense, amount owed to the supplier, output VAT and input VAT.
For example, a purchase for £100.00 of IT services from a supplier, with output VAT and input VAT accounted for:
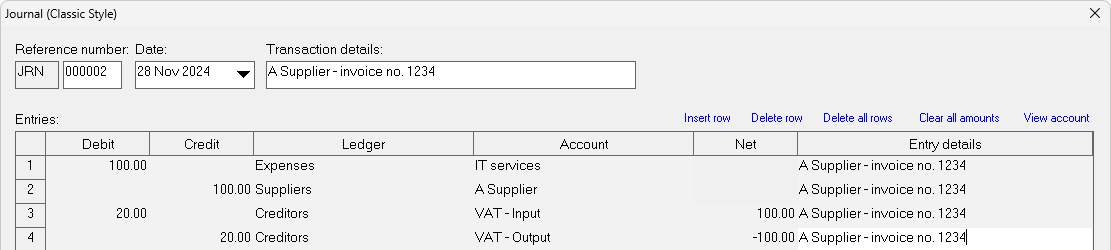
Note: If you are entering a cash purchase (i.e. paid for at the time of purchase), select the bank account instead of the supplier account in the second row.

Running the VAT return
Entering the transaction as instructed above will populate the VAT return with the required values:
VAT return element |
Included in VAT return |
Amount included |
Reverse charged output VAT |
Box 1 |
VAT amt |
Input VAT reclaimable |
Box 4 |
VAT amt |
Net amt (deemed to be a 'supply') |
Box 6 |
Net amt |
Net amt |
Box 7 |
Net amt |
1.The HMRC VAT Cash Accounting Scheme Manual indicates that the scheme does not apply to reverse charge transactions: 'The [VAT Cash Accounting] scheme shall not apply to....supplies of goods or services in respect of which it is for the recipient, on the supplier’s behalf, to account for and pay the VAT.'
